Weekly note · AI · Physical AI · Robotics
Japan's 30% by 2040: Why the Aging Economy Is Becoming the World's Largest Physical AI Deployment Lab
While Silicon Valley argues about AGI timelines, Japan is quietly running the world's most aggressive physical AI deployment program. In March 2026, METI announced a national target of capturing 30% of the global physical AI market by 2040, backing it with ¥387.3 billion in FY2026 alone. Combined with FANUC-NVIDIA voice-to-Python robots, Mujin's autonomous warehouse systems, and a demographic crisis that makes deployment non-optional, Japan has become the most important real-world testing ground for embodied AI on Earth — and the strategic implications for foreign businesses are only beginning to surface.
- Published
- Friday
- Reading time
- 11 minutes
- 5 sections · 4 questions
The short version
5 things to know.
- 01METI announced in March 2026 a national target of 30% global physical AI market share by 2040, backed by ¥387.3 billion in FY2026 funding plus ¥150 billion in next-gen robotics R&D subsidies — the most aggressive industrial AI strategy of any major economy.
- 02Japan starts from a dominant position: Japanese manufacturers held approximately 70% of the global industrial robotics market in 2022. Physical AI extends that lead from precision-engineered machines to autonomous systems that can interpret voice instructions and adapt to changing environments.
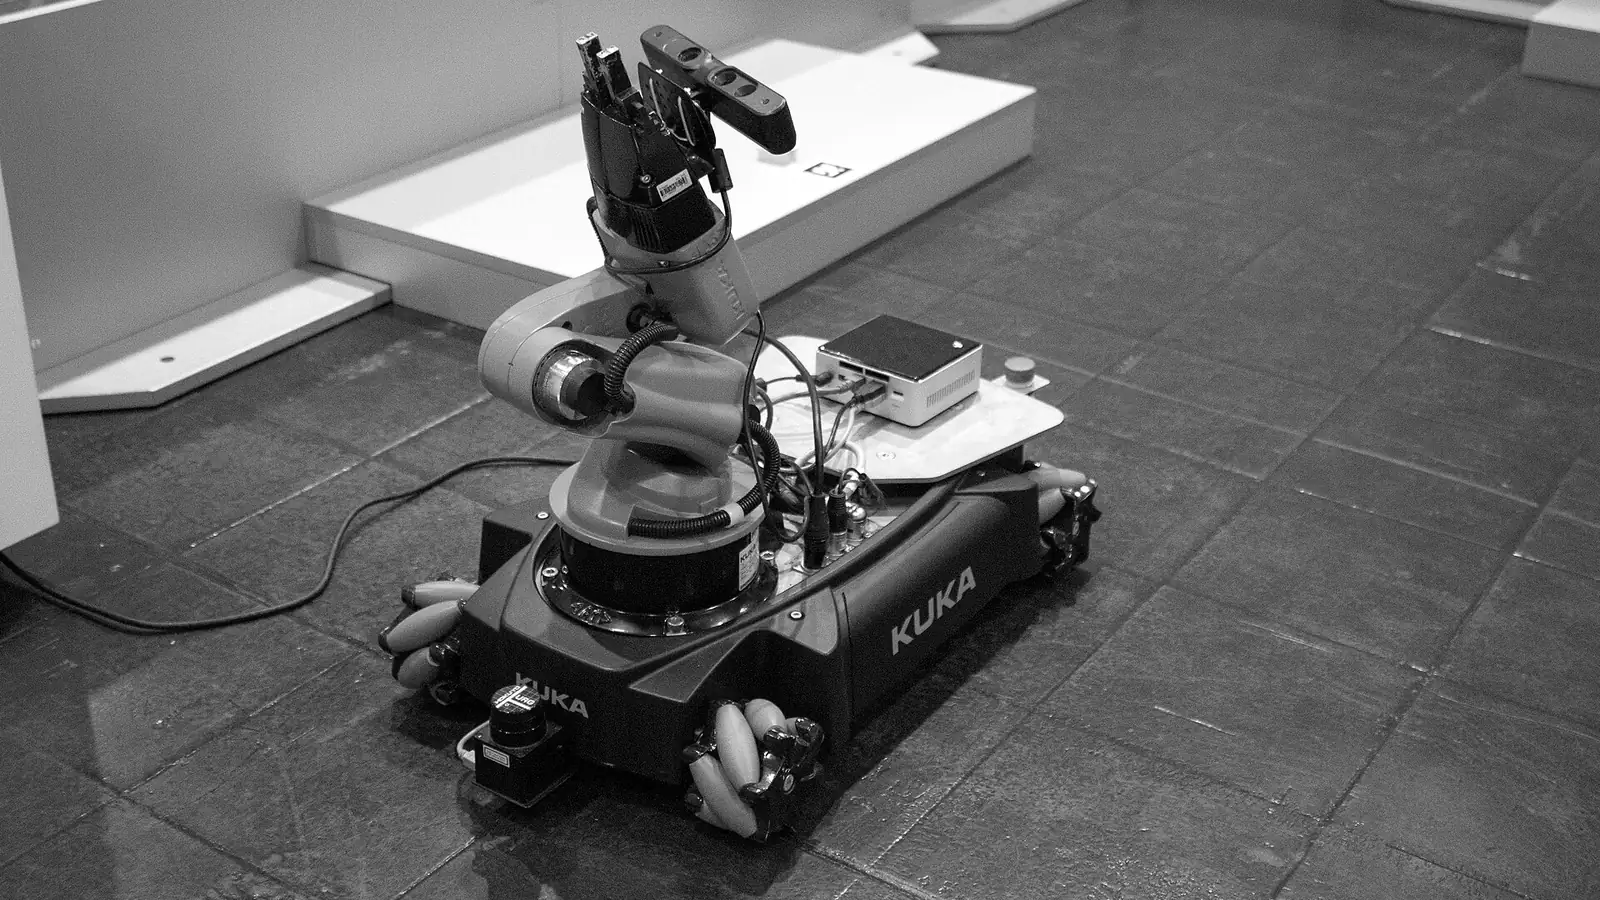
- 03Real-world deployments in 2026 are already at scale: FANUC robots running NVIDIA-powered voice-to-Python code generation, Mujin's autonomous systems handling variable warehouse packaging, and inspection robots in data centers and care facilities.
- 04The deployment is necessity-driven, not hype-driven: Japan's working-age population is projected to shrink by 15 million over the next 20 years, making physical AI a national survival strategy rather than a speculative tech bet.
- 05For foreign brands operating in Japan, partnering with Japanese physical AI players now — before the 2027–2028 commercialization wave — offers access to deployment expertise that won't exist at scale anywhere else for at least a decade.
01 · The 30% GoalJapan Just Made Physical AI a National Industrial Strategy
In March 2026, Japan's Ministry of Economy, Trade and Industry (METI) announced an objective that has barely registered in Western tech press but reshapes how governments are thinking about AI: Japan will pursue a 30% share of the global physical AI market by 2040. The number is striking on its own. The funding behind it is more striking: ¥387.3 billion (approximately $2.5 billion) allocated specifically for physical AI and domestic AI infrastructure in fiscal year 2026, on top of a ¥150 billion subsidy programme for next-generation robotics R&D launched in April 2025.
What separates this from the usual government AI press release is that physical AI is not theoretical for Japan. The country's manufacturers — FANUC, Yaskawa, Kawasaki, Mitsubishi Electric, and Nachi-Fujikoshi — already control roughly 70% of the global industrial robot market. The METI strategy is not asking Japan to build a new industry from scratch. It is asking Japan to extend an existing dominance from precision-engineered hardware into AI-powered autonomous systems, where the global market is currently fragmented and the leader is undefined.
Under Prime Minister Sanae Takaichi, Japan has additionally committed approximately $6.3 billion to strengthen core AI capabilities and accelerate robotics integration. Combined, these allocations form the most coherent industrial AI strategy of any G7 economy. Where the United States debates federal AI regulation and the EU passes the AI Act, Japan is writing checks and pointing them at factory floors.
02Why Japan Can Deploy Physical AI Faster Than Anyone Else
The deployment speed advantage Japan holds over the United States, Germany, and China comes down to three structural factors that no policy package can replicate quickly. The first is demographic. Japan's population has declined for 14 consecutive years; the working-age share has dropped to 59.6% and is projected to lose another 15 million people in the next two decades. In the United States, deploying autonomous systems triggers political fights over job displacement. In Japan, those jobs are vanishing whether the robots arrive or not. The robot is not coming for your job — it is filling a job nobody wants and nobody is left to do.
The second is cultural. Japanese consumers and workers have decades of unbroken comfort with robots in everyday settings — from convenience-store automation to nursing-home companion robots — that simply does not exist in Western markets. When a hotel deploys a humanoid concierge in Tokyo, customers find it normal. When the same robot is deployed in San Francisco, it makes the news. That cultural baseline compresses the trust-building phase that slows physical AI rollouts in other markets by years.
The third is industrial. Japan's keiretsu structures, lifetime employment dynamics, and tightly integrated supplier networks let large manufacturers test and iterate physical AI deployments inside a single corporate umbrella before commercial release. A new robotic system can move from R&D lab to a Honda assembly plant to a partner factory to an external customer through relationships that already exist, with feedback loops measured in weeks rather than quarters.
03 · From Lab Demos to Loading DocksWhat Is Actually Running in 2026
The most concrete sign that Japan's physical AI moment has arrived is the FANUC-NVIDIA collaboration shipping in early 2026. FANUC robots now run NVIDIA AI models that interpret voice commands and automatically generate Python code to execute them. An operator on the factory floor speaks an instruction; the robot writes its own program. This is not a research demonstration — it is shipping product. It compresses the cost of redeploying a robot from days of specialist programming to minutes of natural-language interaction, which fundamentally changes the economics of small-batch and frequently changing production lines.
Mujin, a Tokyo-based startup, has parallel deployments in logistics. Its autonomous systems handle variable packaging and unpredictable warehouse layouts — exactly the conditions that defeated the previous generation of warehouse robotics. Mujin's customers include large 3PL operators and consumer-goods companies that have been unable to fully automate because their inventory mix is too variable. Physical AI removes that constraint.
Beyond manufacturing and logistics, deployments are scaling in inspection and care. Inspection robots are now operating in data centers and industrial sites, where they patrol fixed routes, identify anomalies, and flag maintenance issues without human supervision. In care facilities, AI-augmented robots are filling staffing gaps that have become acute as Japan's elderly population grows faster than the trained workforce can. Each of these deployments individually is unremarkable. Together, they describe a country where physical AI is moving from novelty to infrastructure.
04 · The Cross-Border ImplicationWhy Foreign Brands Should Care Now
For foreign companies operating in Japan or considering market entry, Japan's physical AI strategy creates two intertwined realities. First, Japanese partners — manufacturers, distributors, retailers, logistics providers — will increasingly operate at automation levels that are simply not available in Western markets. A foreign brand selling into a Japanese 3PL network in 2028 will encounter throughput, accuracy, and unit-economics expectations that have been recalibrated by a decade of physical AI deployment that did not happen at the same scale in their home market.
Second, the AI sovereignty dynamic we covered in last week's analysis of DeepSeek V4 and the Japan AI Foundation Model has a physical-world counterpart. Japan is not only building a sovereign AI software stack — it is building a sovereign physical AI deployment ecosystem. Companies that build localized partnerships with Japanese physical AI players now will gain access to deployment tooling, integration patterns, and regulatory pathways that will be much harder to retrofit later. This is the same playbook that defined which foreign brands won in Japan during the 1990s and 2000s manufacturing localization era — but with a compressed timeline.
The natural Medusa Japan parallel is to website and brand localization. The same principle applies: a brand that adapts to Japanese physical infrastructure standards — including increasingly AI-driven warehousing, distribution, and customer-facing operations — performs measurably better than one that imports its global operations playbook unchanged. The competitive question for the late 2020s is not whether foreign brands can ignore Japan's physical AI lead. It is whether they can move fast enough to integrate with it.
05What Businesses Should Do Right Now
The window between the March 2026 strategy announcement and the 2027–2028 commercialization wave is the moment of strategic optionality. After 2028, the cost of integrating with Japan's physical AI ecosystem will rise sharply: expertise will become billable, partnership slots will be filled, and the price of catching up will be measured in lost market share rather than retainer fees. Three concrete steps make sense for any business with Japan exposure or plans for one.
First, audit your Japan operations or planned market entry against current physical AI capability assumptions. If your Japan supply chain assumes manual receiving, manual inventory checks, or manual quality verification, those assumptions are likely already obsolete and will become demonstrably costly within 24 months. The audit is cheap; the retrofit is not.
Second, identify two or three Japanese physical AI partners — robot integrators, logistics automation specialists, or AI-enabled manufacturing services — and begin relationship-building conversations now. In Japan, the time from first introduction to a working pilot is typically 9–18 months. Starting in May 2026 puts a pilot in production by mid-2027, well ahead of the commercialization wave. Third, treat physical AI integration as a strategic capability inside your organization, not an IT project. Companies that build genuine cross-border literacy in this space will outperform those that delegate it to procurement.
Medusa Japan's cross-border strategy team works with international brands at exactly this kind of inflection point — translating Japan-specific industrial dynamics into actionable operational playbooks and helping companies move from awareness to integrated capability before the window closes.
Questions
Questions, answered.
What is "physical AI" and how is it different from generative AI?
Physical AI refers to AI systems that perceive, decide, and act in the physical world — typically through robots, autonomous vehicles, or industrial machines — rather than producing text or images on a screen. Generative AI writes the email; physical AI loads the truck. Japan's strategy focuses specifically on the second category, where its industrial robotics base gives it a structural advantage that pure software-AI markets do not.
Will Japan's physical AI standards become global, the way Japanese automotive quality standards did?
It is the most likely outcome but not yet certain. Japan dominates physical AI hardware manufacturing, has the most aggressive deployment program, and operates the largest real-world test environment. If Japanese deployment patterns prove most reliable across the 2026–2030 wave, they will set de facto global standards in the same way Toyota Production System practices did. The window for shaping those standards is closing fastest for companies that engage early.
How can a foreign brand benefit from Japan's physical AI ecosystem without manufacturing in Japan?
Three primary paths exist. First, partner with Japanese 3PL and warehousing operators who are deploying physical AI now — this gives you operational benefits without infrastructure investment. Second, license deployment patterns and integration know-how from Japanese systems integrators for use in your home market. Third, treat Japan as the proving ground for global product changes: products that work cleanly with Japan's increasingly automated retail and distribution infrastructure tend to be ready for the next wave of automation in the EU and US.
When does the window for early-mover advantage close?
Functionally, the window narrows sharply between mid-2027 and end-2028 as the first commercial deployments at scale generate the case studies, integrators consolidate their practices, and partnership slots fill. After 2028, late entrants face higher costs to access expertise, longer integration timelines, and partnership terms that are less favorable than what early movers secured. The 18–24 months between now and mid-2027 are when the optionality is largest and cheapest to act on.